Key takeaways:
- A multifamily REIT, also called an apartment REIT, owns income-producing apartment properties. It is narrower than the broader residential REIT category.
- REITs generally must distribute at least 90% of taxable income, not 90% of rental income. Dividend tax treatment can differ from qualified stock dividends.
- Listed, non-traded, and private REITs have very different liquidity, valuation, fee, and access considerations.
Multifamily REITs give investors a way to gain exposure to apartment real estate without directly buying, developing, or operating a building. But the label alone does not tell you how easily an investment can be sold, how its value is set, how much debt it carries, or whether its portfolio actually consists of apartments.
A multifamily REIT, often called an apartment REIT, is generally an equity real estate investment trust that owns and operates income-producing apartment properties. Understanding the structure, property mix, operating measures, and market risks is more useful than relying on a dividend yield or a broad residential REIT label.
This guide explains how apartment REITs work, what makes a company a REIT, how investment structures differ, and what to review before researching any security. It is educational only and is not investment, legal, or tax advice.
This guide will answer:
- What is a multifamily REIT?
- How apartment REITs earn money and pay dividends
- What qualifies a company as a REIT?
- How listed, non-traded, and private REITs differ
- The public apartment REIT landscape
- How to evaluate a multifamily REIT
- Risks and market forces that shape apartment REIT results
- How operations and property technology fit the picture
- FAQs
Watch how ButterflyMX works:
What is a multifamily REIT?
A multifamily REIT is usually an equity REIT that owns and operates apartment communities. It earns much of its revenue from resident rent and related property income, then uses that income for property expenses, debt service, capital needs, and distributions to shareholders.
The category matters because residential REIT is broader than apartment REIT. Residential portfolios can include detached single-family rentals, manufactured housing, or other housing types. For example, Invitation Homes primarily owns detached single-family rental homes, so it belongs in the broader residential category rather than an apartment REIT list. A residential REIT overview can be useful context, but property type should drive the classification.
Most multifamily REITs are equity REITs, meaning they own real estate. Mortgage REITs are different: they primarily finance real estate through mortgages or mortgage-backed investments instead of operating apartment properties. The distinction affects how each business earns income and what risks may matter most. Nareit explains the broader REIT framework and the different ways investors can access the sector.
How apartment REITs earn money and pay dividends
An apartment REIT collects rent across a portfolio of properties. Its results can change with occupancy, rents on new and renewal leases, concessions, operating costs, interest expense, property taxes, insurance, and development or redevelopment activity. Rental revenue is important, but it is only one part of the financial picture.
To maintain REIT tax treatment, a REIT generally must distribute at least 90% of its taxable income to shareholders each year. That threshold is based on taxable income, not on rental income. Many REITs distribute more than the minimum, but distributions can change and are not guaranteed. The SEC investor guide to REITs provides a plain-language explanation of this requirement and other investor considerations.
REIT dividends are generally taxed as ordinary income rather than at the lower rates that can apply to many qualified corporate dividends. Actual tax treatment depends on the investor, the account type, the character of the distribution, and current law. A qualified tax professional can explain how those rules apply to a specific situation.
Dividend yield is a point-in-time calculation, not a quality score or a promise of future income. A high yield can reflect a lower share price, a changing distribution, or risks the market is weighing. Review the underlying business before treating yield as a conclusion.
What qualifies a company as a REIT?
REIT status is governed by tax rules with detailed exceptions. At a high level, the rules address how the company is organized, who owns it, where its income comes from, what assets it holds, and how it distributes taxable income. The statutory language appears in 26 U.S. Code Section 856.
- A REIT must generally be managed by trustees or directors, have transferable shares, and meet ownership requirements designed for broad ownership rather than close control by a small group.
- At least 95% of gross income must generally come from specified passive sources, and at least 75% must come from real-estate-related sources.
- At the end of each quarter, at least 75% of assets must generally consist of real estate assets, cash, or government securities.
- The requirement to distribute at least 90% of taxable income is separate from the Section 856 income and asset tests.
These are plain-language guideposts, not a complete legal analysis. Service-income rules can be fact-specific, and taxable REIT subsidiaries or independent contractors may be relevant in certain arrangements. Meeting REIT requirements also does not make a security low risk.
How listed, non-traded, and private REITs differ
The word REIT describes a tax and business structure, not one uniform investment experience. Structure affects how investors buy, value, and exit an investment, as well as what disclosures and fees may apply.
Swipe to compare →
Visible daily price changes can make listed REITs feel more volatile. Infrequent valuations in non-traded or private vehicles may make reported values appear steadier, but they do not remove property, financing, liquidity, or loss risk. Before considering a non-traded or private vehicle, review its offering documents, valuation method, redemption provisions, conflicts of interest, and fee structure.
The public apartment REIT landscape
Company lists become stale quickly as mergers, acquisitions, and changes in portfolio strategy reshape the sector. The following is a classification reference as of October 29, 2026, not a recommendation list or a complete inventory of every public apartment REIT.
Multifamily Dive reported the completion of the AvalonBay and Equity Residential merger in August 2026. Hoya Capital listed Vivmark as the largest tracked apartment REIT by market capitalization on October 29, 2026, a point-in-time observation that should not be read as a quality ranking. Its 2026 apartment REIT sector list is a useful starting point, but every ticker, portfolio statistic, dividend yield, and company status should be checked against current filings or investor-relations materials before publication or investment research.
Likewise, Blackstone confirms the completed acquisition of American Campus Communities. These ownership changes show why a dated list is more useful than a recycled list of familiar names.
How to evaluate a multifamily REIT
A useful evaluation looks beyond a share price, market capitalization, or yield. The following checklist can help readers compare public filings and earnings materials. It is a research framework, not a buy, sell, or hold recommendation.
- Review FFO and AFFO trends. These are widely used REIT performance measures, but company adjustments and reconciliations can differ. Read the issuer definition and reconciliation rather than assuming results are directly comparable.
- Compare same-store NOI and occupancy. Same-store net operating income can help show how a stable pool of properties is performing, while occupancy indicates how much available apartment space is leased. Check the reporting period and which communities are in the same-store pool.
- Separate new-lease from renewal-lease growth. New leases reflect current market conditions, while renewals reflect existing residents. The two can move in different directions when supply or demand shifts.
- Examine leverage and debt maturities. Consider total debt, borrowing costs, fixed- versus variable-rate exposure, maturity dates, development commitments, and the company ability to fund acquisitions or redevelopment.
- Study market concentration. A coastal or Sun Belt label is not enough. Look at local employment trends, apartment supply, household formation, regulation, and the share of the portfolio in each market.
- Assess management and capital allocation. Review whether management is buying, selling, developing, redeveloping, or repurchasing shares, and how those choices fit the balance sheet and property conditions.
The same operating, balance-sheet, and market criteria are useful whenever you compare apartment REITs. No single metric can establish property value or investment quality on its own.
Risks and market forces that shape apartment REIT results
Apartment demand can be affected by local jobs, household formation, affordability, and consumer confidence. At the same time, new apartment construction can add competing units, putting pressure on occupancy, concessions, and new-lease rent growth. The impact varies greatly by city and submarket.
Interest rates matter in several ways. They can affect a REIT borrowing costs, refinancing needs, development decisions, transaction activity, and the cap rates investors use to value real estate. A cap rate is a property valuation measure that relates income to value; changes in cap rates can influence estimated property values even when a building income is unchanged.
Rent regulation, housing policy, property taxes, insurance costs, and zoning conditions are also local risks, not universal conditions. A portfolio spread across markets may reduce concentration in one place, but it can also add exposure to several different regulatory and economic environments.
Market narratives need dates. In an August 2025 discussion, analysts quoted by Nareit described heavier Sun Belt supply and stronger coastal performance during the conditions then being discussed. That historical context is not a current forecast and should not be treated as a permanent geographic advantage. REIT status does not make a listed security immune to volatility or market losses.
How operations and property technology fit the picture
For apartment owners and operators, financial results begin with day-to-day property operations. In the August 2025 Nareit discussion, analysts identified resident experience, retention, ancillary services, and automation as management priorities. Those observations describe management focus during that period, not a universal finding that any particular technology raises rent, retention, net operating income, or investment returns.
Access workflows are one operational area an apartment operator may evaluate. Resident entry, visitor arrivals, deliveries, elevator permissions, and staff administration all involve decisions about convenience, oversight, integrations, rollout requirements, and cost. The right approach depends on the property and the operating model.
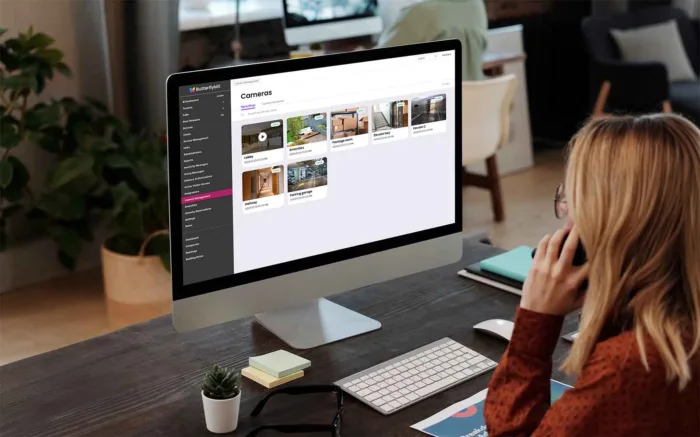
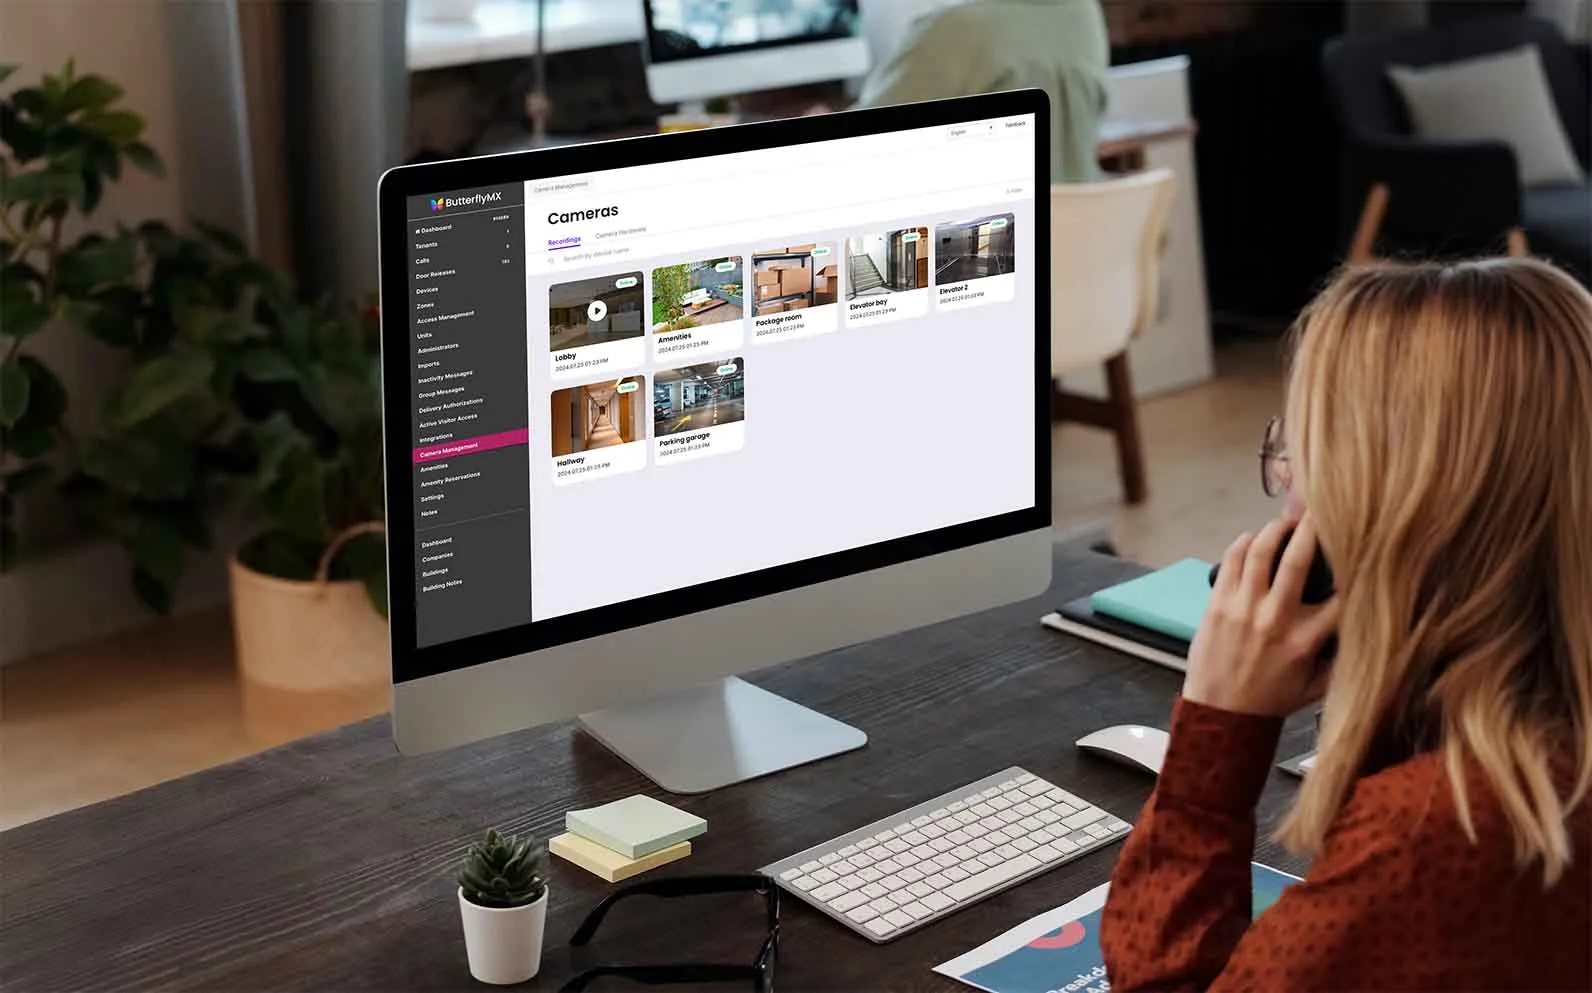
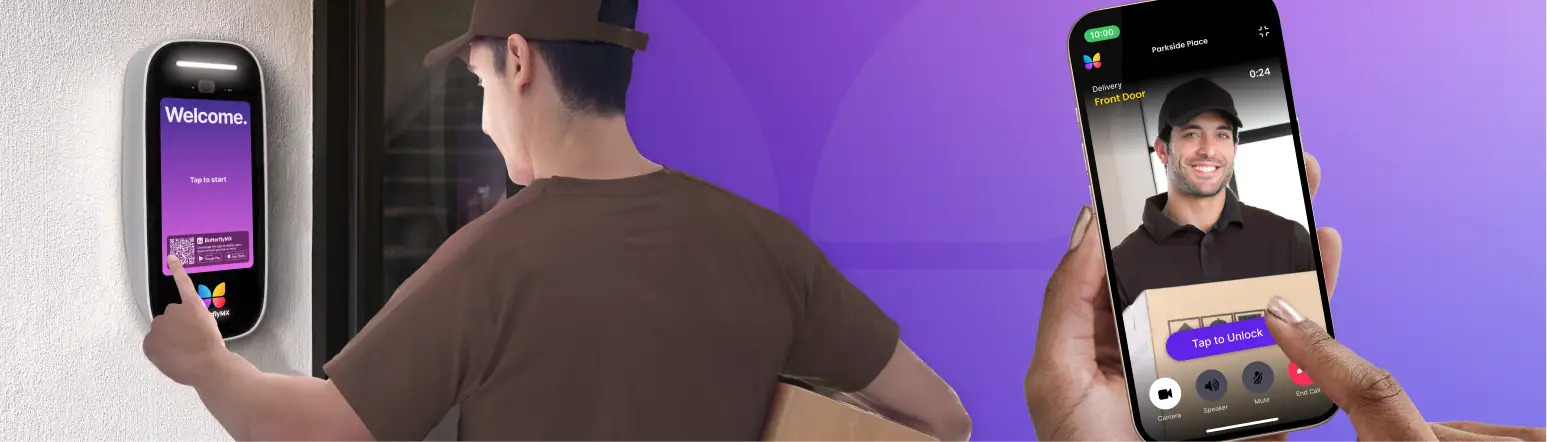
For example, ButterflyMX offers multifamily access control capabilities including smartphone entry, video intercoms, visitor and delivery access, elevator controls, and cloud-based administration. Residents can receive visitor calls and grant access through their smartphones, while property teams can manage people and credentials remotely. Owners and managers should evaluate product fit, integrations, administration needs, and deployment requirements for their own portfolios rather than assume financial outcomes from technology adoption.
Frequently asked questions
What happened to AvalonBay and Equity Residential?
AvalonBay and Equity Residential completed their merger in August 2026 to form Vivmark Residential, which trades as VMRK. They should not be treated as separate current public securities; corporate status and ticker information should still be checked immediately before publication or research.
Is Invitation Homes a multifamily REIT?
No. Invitation Homes primarily owns detached single-family rental homes, placing it in the broader residential REIT category rather than an apartment REIT category.
Can investors get apartment REIT exposure through an ETF or mutual fund?
Potentially, but a fund may hold several real estate sectors rather than only apartment REITs. Review current holdings, concentration, fees, and the fund methodology before assuming it provides pure apartment exposure.
Are non-traded REITs safer because their reported values move less often?
No. Less frequent valuation can make reported values appear less volatile, but it does not remove property, financing, liquidity, or loss risk. Redemption terms and valuation practices vary by offering.
Are apartment REIT dividends taxed like qualified stock dividends?
Generally, no. REIT dividends are often taxed as ordinary income rather than at the lower rates that may apply to many qualified dividends, though individual treatment depends on current law, account type, and the investor circumstances.
Do apartment REITs use building and access technology?
Many operators evaluate technology for resident, visitor, delivery, and staff workflows. Technology adoption alone does not establish rent, retention, NOI, or investment-performance results.
Multifamily REITs can provide exposure to apartment real estate, but they are not interchangeable investments. Start with property type and REIT structure, then examine operating trends, leverage, local supply, and management decisions before drawing conclusions from a yield or a familiar company name.
For apartment owners and operators, property technology is a separate operational decision that should be evaluated on its own merits. Explore ButterflyMX access solutions for multifamily properties when resident, visitor, delivery, and access-management workflows are part of that review.
Get your free quote!
Fill in the form below, and we'll email you right back.
Want a free quote?
Fill in the form below, and we'll email you right back.
You’ll be redirected shortly...